Josh Kadish on POWER FM: South Africa's SMME funding gap is a readiness problem
Sourcefin CEO Josh Kadish joined POWER 98.7's POWER Lunch to unpack purchase order financing, the SMME funding gap, and the FNB referral arrangement.

On this page
- Key takeaways
- The R350 billion question: is it really about money?
- What purchase order financing actually solves
- Why a confirmed order doesn't guarantee approval
- Beyond the "tenderpreneur" label
- Sourcefin and FNB: closing the gap together
- A live caller puts it to the test
- How SMMEs can get in touch with Sourcefin
- Frequently asked questions
Purchase order financing is now central to closing South Africa's SMME funding gap, Sourcefin CEO Josh Kadish told POWER 98.7's POWER Lunch on 7 September 2026. The real barrier isn't a shortage of money: it's that many SMMEs with confirmed orders aren't yet ready for the finance that already exists to fund them.
Key takeaways
- South Africa's SMME funding gap is often framed as a shortage of capital, but Sourcefin's experience points to a readiness gap instead.
- Purchase order financing unlocks capital against a confirmed order, so an SMME can pay its suppliers before its own client pays.
- Traditional banks assess a deal on collateral and history, while Sourcefin assesses whether the order itself is viable and deliverable.
- Not every purchase order or tender belongs to a "tenderpreneur" – the large majority are legitimate businesses delivering real work to real clients.
- Through a referral arrangement with FNB, more SMEs banking with FNB can now be considered for purchase order financing.
The R350 billion question: is it really about money?
Every few months, a new report puts a number on South Africa's SMME funding gap, and R350 billion is the figure doing the rounds in 2026. Kadish didn't dispute the number when POWER Lunch host Kwena Moabelo put it to him. He reframed it.
"There's a lot of good happening in this space, but we still struggle, especially with access, and I think readiness," Kadish said. "A lot of the SMEs don't know that products like purchase order financing exist. It's about knowing where to go, how to pitch your business. And also your readiness of your business."
That framing lines up with the research behind the headline figure. A 2025 national access-to-finance study, compiled with Experian, Stellenbosch University's Bureau for Economic Research, the International Finance Corporation and the Department of Small Business Development, put the gap at over R350 billion and concluded it isn't driven by a lack of capital at all. It's a mismatch between what funders need to see and what most applicants can currently show them.
What purchase order financing actually solves
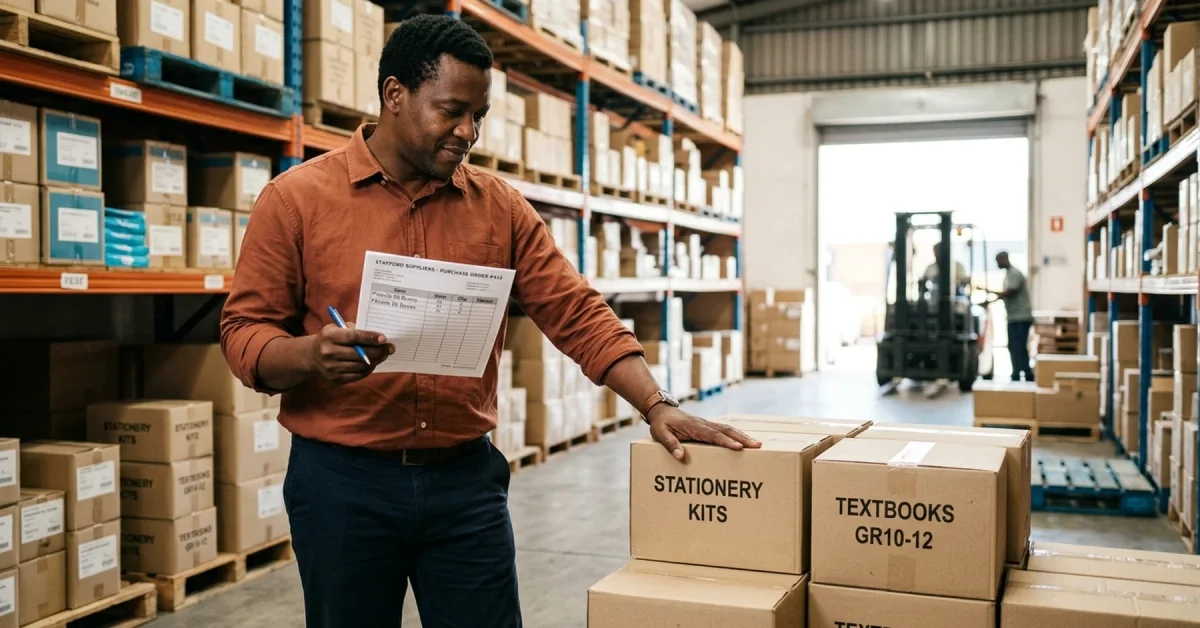
Asked to explain the product in plain terms, Kadish reached for a scenario every listener could picture: a small business that's won an order to deliver textbooks and stationery to a school.
"They'll be buying those textbooks from, you know, maybe the printers. They're going to be getting stationery from the wholesalers. And they've got commitments in terms of their working capital... usually their clients will only pay them after delivery, and very often 60 days later. So now what you're looking at is a very clear cash flow mismatch, because you need to put your cash out to purchase your stock, to purchase the materials to deliver, but you're only getting paid 30 or 60 days later. What purchase order financ[ing] does is it takes that committed order, that piece of paper, that contract, and it allows us to finance off the back of that. We will pay your supplier, and you only repay us once your client has paid you. That's the key. Your debt only becomes due once you've been paid. It's really the bridge that exists."
It's a plain description of a problem most SMME owners live with daily: the work is real, the client is real, and the cash still doesn't arrive in time to pay for it.
Why a confirmed order doesn't guarantee approval
Moabelo's follow-up question is the one every SMME owner with a signed purchase order wants answered: if the order is confirmed, why would anyone still say no?
"If they've got a committed order, it's the biggest first step that they need. The next question comes in is, is that order viable? Sometimes customers misprice. I always think of laptop deals, because those often exist, where a certain specification of a laptop is required and the client underprices on it. So you need to make sure it's viable. Is there profit in this deal? Does the timing exist? Can we get that stock? Working with Sourcefin means we work with you. We've done over 2,000 deals. We've got over 3,000 trusted suppliers. We will help you find the best supplier. So the key is, is that committed order worth something? And if it is, Sourcefin can be your partner to make it really turn into cash."
It's a useful distinction: the paperwork proves the order exists, but it doesn't prove the deal makes commercial sense. Sourcefin's role, on Kadish's account, is doing that second check with the business rather than for it.
Beyond the "tenderpreneur" label
Moabelo raised the question most South Africans reach for the moment tenders come up: the tenderpreneur problem. Kadish's answer was direct.
"There's a negative perception and a connotation to the word tender and tenderpreneurs. Firstly, purchase orders exist in the private and public sector, and they're not uniquely South African. Tender essentially means an invitation to do business and win a contract. We work very closely with our clients, we meet all of them, and for the gross majority we've ever worked with, they're really good people with good businesses, good contracts. It's your guys on the ground. It's your plumbers. It's your logistics companies. Unfortunately, a small, very loud group has tainted the environment. Do bad actors exist? Yes. Are those the clients we serve? No. I'm an attorney by profession. There are some really bad attorneys that have done bad things. It doesn't mean all attorneys are bad. You've just got to understand this is an area South Africans are fascinated by, but it doesn't mean you should paint everyone with that brush."
Sourcefin and FNB: closing the gap together
The interview's most substantial news wasn't a new statistic. It was Kadish's description of how the referral arrangement between Sourcefin and FNB actually works for an SMME on the ground.
Kadish called it an arrangement the team is genuinely proud of, one that took three to four years to get over the line. "FNB is the biggest financier of SMEs on the continent. From a transactional banking perspective, they're unrivalled in our space," he said. "It's the bridging of them as the transactional banker and Sourcefin as the purchase order funder. The bank are taking it seriously and saying, our framework doesn't allow us to fund these people because we don't have this type of product in our repertoire. But Sourcefin are the guys to do it. If you are an FNB business client and you believe this is a product you're looking for, you can get in touch with your banker, explain the funding you're looking for, and they will make that introduction."
He went on: "For a company like ours, which is just under 6 years old, to have the might of an FNB to say, you guys are our partner, we're going to trust you with our clients – that was a massive moment for us. Our goal is to distribute our product to as many SMEs in South Africa. Everyone reports R350 billion. Let's see how we can chip that away, one billion at a time, and make sure SMEs in this country continue to thrive."
A live caller puts it to the test
The clearest proof of the interview's reach came near the end, when Moabelo read out a question from a listener on X.
"I'm in a lucrative industry, construction and mining, that needs real funding. My annual bank statements are over 3 million revenue, but I'm still struggling because of my credit score. Can Sourcefin help?"
Kadish's answer was immediate: "Perfect type of client for us. He's probably got a great contract or great opportunities, but maybe some hard credit scores – we all know COVID hurt everyone, there might be legacy issues there. The beauty of Sourcefin is what we evaluate is your contract. Provided you have these opportunities and this work, we're exactly the partner you should look for. There's good track record and good revenue, and we're not too worried about your credit score. Our job is to make sure that order can be executed on, and we can help you with working capital."
How SMMEs can get in touch with Sourcefin
Kadish closed with the same answer he gives every caller: "You'll find us on sourcefin.co.za, or you can Google Sourcefin and look us up on social media. And if you're an FNB business client, you're welcome to reach out via your banker and ask for a referral to Sourcefin. We'll invite you to the office, we'll look at your deal, and hopefully we can fund you."
For SMME owners who recognise their own business in this conversation – a confirmed order, real work, a cash flow gap standing in the way – the full guide to purchase order financing in South Africa is the next stop, and the honest guide to who qualifies tackles the credit-score question in more depth. Ready to put a confirmed order to work? Apply for purchase order financing directly with Sourcefin.
This wasn't Sourcefin's first time on POWER 98.7. The station covered the City of Joburg collaboration in an earlier POWER Business interview, and this latest conversation picks up the same thread: real businesses, real orders, and the funding to deliver on them.
Sources & references
Frequently asked questions
What is the Sourcefin and FNB referral arrangement?
Through a referral arrangement with FNB, eligible FNB business clients with a confirmed purchase order or tender can be referred to Sourcefin for purchase order financing. FNB brings its trusted banking infrastructure and makes the introduction, but Sourcefin assesses every deal independently and makes the funding decision itself.
Why would a bank decline an SMME that already has a confirmed purchase order?
A confirmed order is the starting point, not the whole picture. A bank still needs to check that the order is priced correctly, that the goods or services can genuinely be delivered in the required timeframe, and that there's real profit left once input costs are covered. Sourcefin works through those questions with the SMME rather than declining on paperwork alone.
Is purchase order financing only used for government tenders?
No. Purchase orders and tenders exist in both the private and public sector, and the practice isn't unique to South Africa. Sourcefin funds confirmed private-sector orders as often as it funds tenders, and judges each SMME on the strength of its contract and its ability to deliver, not on the source of the order.
Can an SMME get funding with a poor credit score if it has a strong contract?
Often, yes. Sourcefin's assessment centres on the confirmed order itself, the business's revenue and delivery track record, and whether the end buyer can pay, rather than treating a weak credit score as an automatic decline. A legacy credit issue doesn't rule a business out if the underlying opportunity is sound.
Sourcefin is a South African alternative finance provider that offers purchase order funding and invoice discounting to SMMEs, enabling businesses to fulfil confirmed purchase orders or tenders and unlock cash flow without collateral. Unlike traditional lenders or banks, Sourcefin also provides end-to-end support including supplier sourcing, logistics, project management, and risk oversight.